INFONAVIT for Manufacturers: Budgeting the 5% Employer Contribution
7 min Read
Key Takeaways
- INFONAVIT is Mexico's national worker housing fund, and employers pay 5% of each worker's contribution salary whether or not the worker has a housing loan.
- The 5% applies to the contribution salary, which includes the proportional aguinaldo and vacation premium, so 5% of base wages alone can understate it.
- The contribution salary is capped at 25 times the UMA, which works out to MXN 2,932.75 a day from February 1, 2026.
- Housing-loan repayments are a separate deduction from the worker's pay, withheld and remitted by the employer every two months alongside the contribution.
- From the November and December 2025 pay period, fixed loan deductions are not reduced for absences or certified incapacity leave, within wages paid and legal limits.
Jump to Section
Once a Mexico expansion estimate moves past the building and into payroll, the line items start to multiply: wages, social security, the aguinaldo, vacation premium, and a housing contribution called INFONAVIT. It is easy to enter that last one as a single line, five percent of base wages, and move on. The rate is the easy part. What can get missed is the salary the rate is applied to, and a second INFONAVIT amount that runs through the same payroll without being an employer cost at all.
The short answer: INFONAVIT is Mexico’s national worker housing fund. On a Mexico payroll it brings two obligations. The employer pays a 5% contribution on each worker’s contribution salary, whether or not the worker has a housing loan. For workers who do, payroll also withholds the loan repayment from their pay and sends it to INFONAVIT.
What INFONAVIT is, and why it sits in your payroll costs
INFONAVIT, the Instituto del Fondo Nacional de la Vivienda para los Trabajadores, was created by a law published in April 1972. It runs the national fund that lends formal-sector workers the money to buy, build or improve a home, and employers pay into it. That is why it shows up on Mexican payrolls, from a small office to a plant running three shifts, and why it belongs in a labor estimate from the first draft.
The contribution applies whether or not the worker has a housing loan. For example, an operator with no plans to buy a home still receives the employer contribution in their housing subaccount.
For a manufacturer, that puts INFONAVIT in the same family of payroll costs as the employer’s social security contributions to IMSS, the aguinaldo, Mexico’s mandatory year-end bonus, and the vacation premium. It is set by law, so it is neither a benefit you choose to offer nor something you negotiate. The employer contribution rate is 5%, and it is unchanged in 2026. What you can get right is the size of the line, and that comes down to which salary the 5% is applied to.
The 5% is charged on the contribution salary
The law sets the rate at five percent of the worker’s salary and takes its definition of salary from the Social Security Law. That definition is broader than the daily wage. The contribution salary, or salario base de cotización, folds in what a worker receives for their work: the daily wage plus the proportional share of the aguinaldo and the vacation premium, along with other compensation included under the applicable rules.
So an estimate that multiplies base wages by 5% can understate the contribution. The gap is small for one worker, but it is built into every hour you staff, and it widens as seniority adds vacation days and as other pay that enters the base, such as some bonuses and premiums, is added.
There is also a ceiling. The contribution salary is capped at 25 times the UMA, the Unidad de Medida y Actualización, which is the reference unit Mexico uses in place of the minimum wage for caps and fines. The 2026 UMA is MXN 117.31 a day, in effect from February 1, 2026, which puts the ceiling at MXN 2,932.75 a day. The ceiling applies to the daily salary used in the calculation. It matters when an employee’s integrated contribution salary exceeds that amount.
A worked example: one operator’s contribution
Take a first-year operator paid an illustrative MXN 400 a day, with fixed pay and the legal minimum benefits: 15 days of aguinaldo, 12 vacation days and a 25% vacation premium. Nothing else enters the base, and the period is 60 contribution days with no absences or other adjustments.
| Calculation | Amount |
|---|---|
| Daily base wage (illustrative) | MXN 400.00 |
| Integration factor: 1 + (15 + 12 × 25%) ÷ 365 | 1.049315 |
| Daily contribution salary, rounded | MXN 419.73 |
| Employer contribution for 60 contribution days: 419.73 × 5% × 60 | MXN 1,259.19 |
| 5% applied to the base wage alone | MXN 1,200.00 |
That is the gap. Using the integrated contribution salary adds MXN 59.19 over this 60-day period compared with applying 5% to the daily wage alone. In the INFONAVIT contribution, that is approximately 4.93% more. It does not mean total labor cost rises by the same share. The factor shown reflects the stated benefit assumptions. Different benefit entitlements change that factor, while other includable compensation may also increase the contribution salary, so your own roles need their own calculation. The other lines that sit beside this one are laid out in what it costs to manufacture in Mexico.
Then check the other direction before you add INFONAVIT to anything. If you are working from a fully fringed labor estimate, including the figures in our manufacturing wage benchmarks, see whether the housing contribution is already in it. Fully fringed figures usually include it, and adding it a second time overstates the cost.
Housing-loan deductions are a different amount
The second INFONAVIT amount on a payroll belongs to the worker. When a worker takes an INFONAVIT loan, the institute notifies the employer, and payroll withholds the repayment from the worker’s wages and sends it on. It works like income tax withholding: the employer’s responsibility is to calculate, withhold and remit it correctly. The repayment does not change the employer’s 5% contribution, which is why it is tracked separately when you build a labor-cost estimate.
Both amounts travel on the same clock. The employer contribution and the loan repayments are reported and paid every two months, by the 17th of the month after each two-month period, moving to the next business day when the 17th is not one, according to INFONAVIT’s employer payment guidance. That is a different rhythm from the payroll itself, which for operators often runs weekly.
The 2025 reform changed one detail that matters to anyone already running a Mexican payroll. Under INFONAVIT’s published guidance, a repayment set in pesos, or as a fixed number of times the minimum wage (VSM), is not reduced because a worker was absent or on certified incapacity leave. The deduction is still limited by the wages actually paid and by the legal limits on wage deductions. When one of those limits leaves part of a repayment undeducted, the guidance says the employer has no obligation for that part. The change does not affect the 5% employer contribution. The new treatment applies from the pay period covering November and December 2025.
INFONAVIT on a Tetakawi Campus
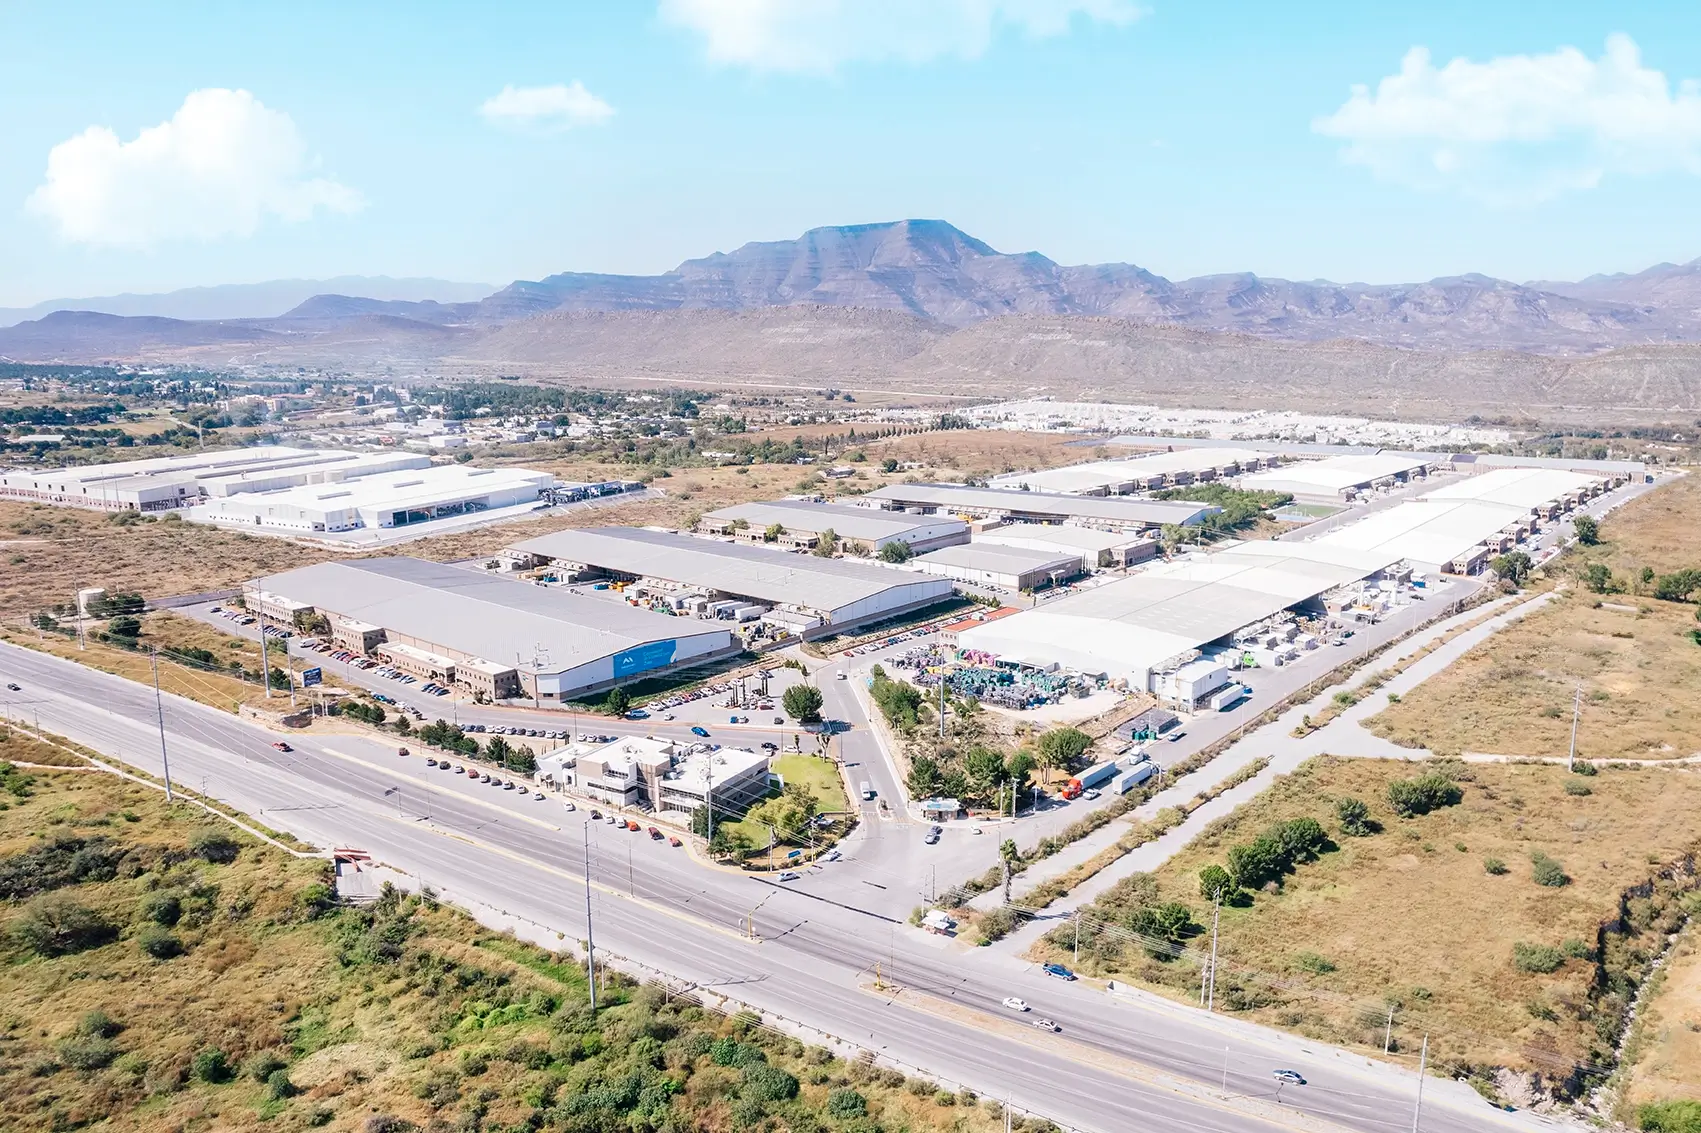
If you plan to run your own production in Mexico, two common routes are worth comparing. You can form your own Mexican company, which then employs the workforce and carries the payroll obligations. Or you can work through a shelter, where, in the usual arrangement, a Mexican company that already holds the registrations employs the workforce and handles the administration while you run production. Tetakawi’s Manufacturing Campuses run on the shelter model. A Manufacturing Campus is an established industrial site in Mexico that Tetakawi runs, where you operate your own factory and Tetakawi runs everything around it. A Campus adds established industrial space, shared infrastructure and an on-site support organization.
On a Campus, recruiting, employment, payroll and benefits run through Tetakawi’s Mexican operations, and INFONAVIT is part of that HR and payroll administration. This includes enrolling each employee for housing and making the employer’s filings for housing. You see and approve the payroll before it runs. You control production, process and quality.
So whichever route you take, the questions to put to any Mexico labor estimate are the same. Which salary was the 5% calculated on? Is the housing contribution already inside the fully fringed figure? And if you already run a Mexican payroll, how does it treat fixed loan deductions when a worker is absent?
Frequently asked questions
Do foreign manufacturers in Mexico have to pay INFONAVIT?
Yes. The contribution is a legal obligation of the employer for the workers on its Mexican payroll, whatever the nationality of the company that owns the plant.
What is the INFONAVIT employer contribution rate in 2026?
5% of each worker’s contribution salary. The contribution salary includes the proportional aguinaldo and vacation premium, and it is capped at 25 times the UMA. With the 2026 UMA of MXN 117.31 a day, in effect from February 1, 2026, the cap is MXN 2,932.75 a day.
Does the contribution apply if a worker has no INFONAVIT loan?
Yes. The 5% goes into the worker’s housing subaccount whether or not they borrow. The loan repayment is the separate amount, and it applies only to workers who have an INFONAVIT loan.
How often is INFONAVIT paid?
Every two months. Employer contributions and loan repayments are paid by the 17th of the month after each two-month period, or the next business day when the 17th is not one.
Talk through your Mexico labor costs
Tell us what you plan to make in Mexico and how many people you expect to need. We will walk through how a Campus would support it.
Subscribe to stay up to date with our latest insights